
Esports
Why Esports Platforms Need Different Payment Rails Than Traditional Game Stores

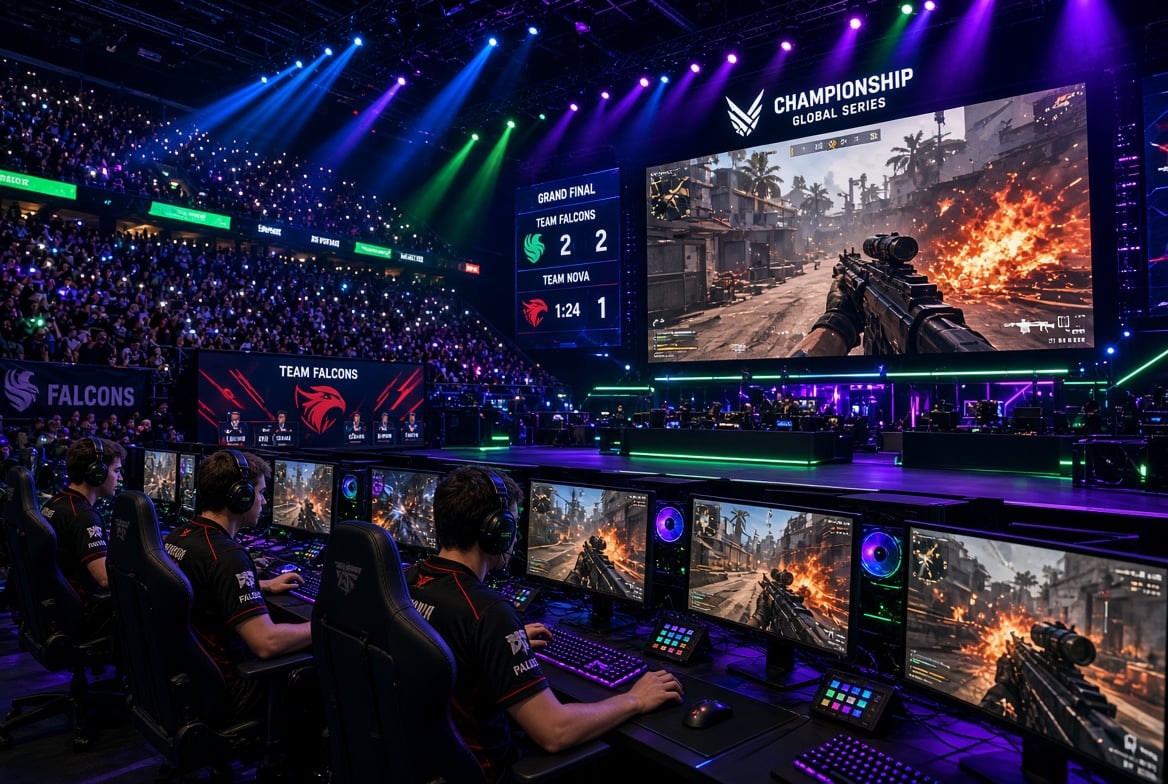
The two businesses look interchangeable from the outside. Both sell to an audience under 35, both collect money through a phone, and both measure success in conversion rates on a checkout screen. Engineers who have built one often assume the second is the same system with different artwork.
A game store moves money in one direction, from a customer who owns nothing until the transaction completes. An E-Sports platform holds customer funds, returns them on demand, and answers to a regulator in every state where it operates. Those two facts change the payment stack from the checkout down.
One Customer, Two Regulatory Positions
A store sells an entitlement. The buyer pays, the account receives a skin or a season pass, and the obligation ends. Consumer law applies, card network rules apply, and nothing else does. A betting platform takes a deposit into an account the customer still owns. That balance is a liability on the operator’s books until it is withdrawn or lost, and the operator has to prove to a state regulator that it knows who owns it. The card transaction that starts the relationship is the smallest part of the compliance surface around it.
Money Moving in Both Directions
Store engineers underestimate payouts first.
A store almost never sends money to a customer, and when it does the refund reverses an original transaction that already exists in the system.
A betting platform sends money to people who never bought anything from it. A withdrawal has no original sale to reverse, so it moves over a payout rail rather than a refund path, usually a push to the debit card on file or a bank transfer. Both come with their own limits and failure modes, and customers judge the entire operator on how fast that money arrives. An operator with a two-day payout, next to a competitor that pays in 30 minutes, loses customers over treasury mechanics it never describes to them.
Identity Checks Before the First Deposit
Age and identity verification runs before the money does. A store checks a card. An operator checks a person against records, confirms an address, and in most states confirms the customer is physically inside the border at the moment the bet is placed. A failed check has to stop the deposit rather than the payout, because money taken from someone who cannot legally hold an account is a refund plus a filing.
This is where igaming payment processing separates from ordinary checkout work. The processor has to pass verification results, geolocation flags, and account status into the authorization decision, and it has to keep records that survive an audit years later. A store checkout that approves in 1.2 seconds and forgets the customer is doing a different job.
State Licensing and Card Acceptance
There is no national permission slip. The Supreme Court struck down the federal ban in 2018, which allows sports betting only where a legislature has since said yes, and esports wagering has an extra layer of state-by-state treatment that leaves it legal in some markets, banned in others, and unaddressed in the rest.
The operational consequence is that one company operates under several sets of rules at once. Products differ by state, so the checkout has to know which state the customer is in before it knows what it is allowed to sell. Card issuers add their own layer, since some banks decline transactions coded to gambling categories regardless of legality, and a decline rate that would be a crisis for a store is routine for an operator. Building around that means alternate funding methods, retry logic that respects issuer rules, and reporting that separates a compliance decline from a fraud decline.
Refund Rules in a Game Store
The store side has its own obligation, and it is consumer protection rather than licensing. Epic agreed to pay $245 million in 2022 over charges the Federal Trade Commission said customers never meant to make, and the distribution has run in rounds since, with $72 million sent in December 2024 and more than $126 million in the round that followed.
A store’s payment stack answers that with product design. Purchase flows need a confirmation step a child cannot pass by accident, and refund tooling that can process a bulk order without an engineer writing a script at midnight. An operator’s system needs none of that, and a store’s system needs it more than it needs a payout rail.
Store Commissions and External Checkout
Distribution changes the economics on the store side again. A studio selling through a mobile store handed over 30% of every sale, and the fight over that number reshaped how game purchases are built. Apple changed its US App Store rules in May 2025 to let apps link out to their own checkout, after a court found the previous setup defied an earlier injunction.
That opening is why studios now run web shops and why a game company suddenly needs merchant accounts and fraud tooling it never owned before. A betting operator has always owned those pieces, because no mobile store has ever processed a wager on its behalf.
Two Different Fraud Profiles
Fraud teams on both sides use the word fraud for different behavior. A store fights stolen card numbers and account takeovers aimed at reselling inventory. Losses are per transaction and the pattern is familiar to any online retailer.
An operator fights bonus abuse, multi-accounting, collusion between accounts, and the slower problem of people with access to an outcome. ESPN’s running account of sports gambling scandals since 2018 reaches players and referees alike, and integrity monitoring is now part of the same data layer that scores payments. A store has no equivalent problem, because nobody rigs the outcome of a cosmetic purchase.
The tooling follows from that difference. A store caps its exposure with per-transaction limits and a velocity rule, and a card approved once will usually be approved again. An operator needs rules that read a customer’s whole history across deposits and withdrawals, since abuse funded through one channel leaves through another days later, often through a second account registered to the same address. Scoring written against single transactions misses the pattern completely, which is why operators end up buying risk tooling built for banks rather than the fraud screen bundled with a checkout.
Separate Stacks for Separate Obligations
An operator that borrows a store’s payment architecture discovers the gaps in a specific order. Payouts come first. Then comes the audit that asks for two years of verification records nobody kept.
The cost of finding out late is measured in license conditions rather than engineering hours. A regulator that finds an operator took deposits it should have refused can suspend the market, and a suspended market pays nothing while the fix is built. Engineering time goes there first, ahead of the checkout.


Why Esports Platforms Need Different Payment Rails Than Traditional Game Stores

Anime You’ll Be Glad You Added to Your Fall Watchlist (Part 2) 🍂

Minecraft All Biomes Seeds for Players Who Love Exploring

Double-Sentinel Defensive Holds Disrupt Fast Valorant Site Executes

Blox Fruits Physical vs Permanent Fruits: What’s the Difference?

What to Check Before Buying FC 27 Coins Online

Pokémon Announces New Movie With a New Hero and Mimikyu

Can You Stream Kick on Xbox: Complete Guide for Xbox Users

6 Years Later, Haikyu!! Returns in the Last Way Fans Expected

From Arcade Cabinets to Digital Cards: The Psychology of the Push-Your-Luck Mechanic

Why Randomness Makes Some Video Games So Interesting

Struckd on Windows: Making 3D Games Without Writing a Line of Code

Why Side Activities Make Open Worlds Feel More Alive

Anime You’ll Be Glad You Added to Your Fall Watchlist (Part-1)

Keyboard vs Controller Gaming: Which One Is Better?

5 Masterful Video Games Where The Element of Chance Shaped the Narrative
-
 Anime3 weeks ago
6 Years Later, Haikyu!! Returns in the Last Way Fans Expected
-
 Features2 weeks ago
From Arcade Cabinets to Digital Cards: The Psychology of the Push-Your-Luck Mechanic
-
 Features3 weeks ago
Why Randomness Makes Some Video Games So Interesting
-
 Features2 weeks ago
Struckd on Windows: Making 3D Games Without Writing a Line of Code
-
 Features2 weeks ago
Why Side Activities Make Open Worlds Feel More Alive
-
 Anime4 weeks ago
Anime You’ll Be Glad You Added to Your Fall Watchlist (Part-1)
-
 Features3 weeks ago
Keyboard vs Controller Gaming: Which One Is Better?
-
 Features3 weeks ago
5 Masterful Video Games Where The Element of Chance Shaped the Narrative
-
 Anime2 days ago
Anime You’ll Be Glad You Added to Your Fall Watchlist (Part 2) 🍂
-
 Games That Changed Our Lives4 weeks ago
The Best Ways to Play a Modpack With Friends
-
 Anime1 week ago
Pokémon Announces New Movie With a New Hero and Mimikyu
-
 Features3 weeks ago
How to Actually Read a WoW DPS Tier List